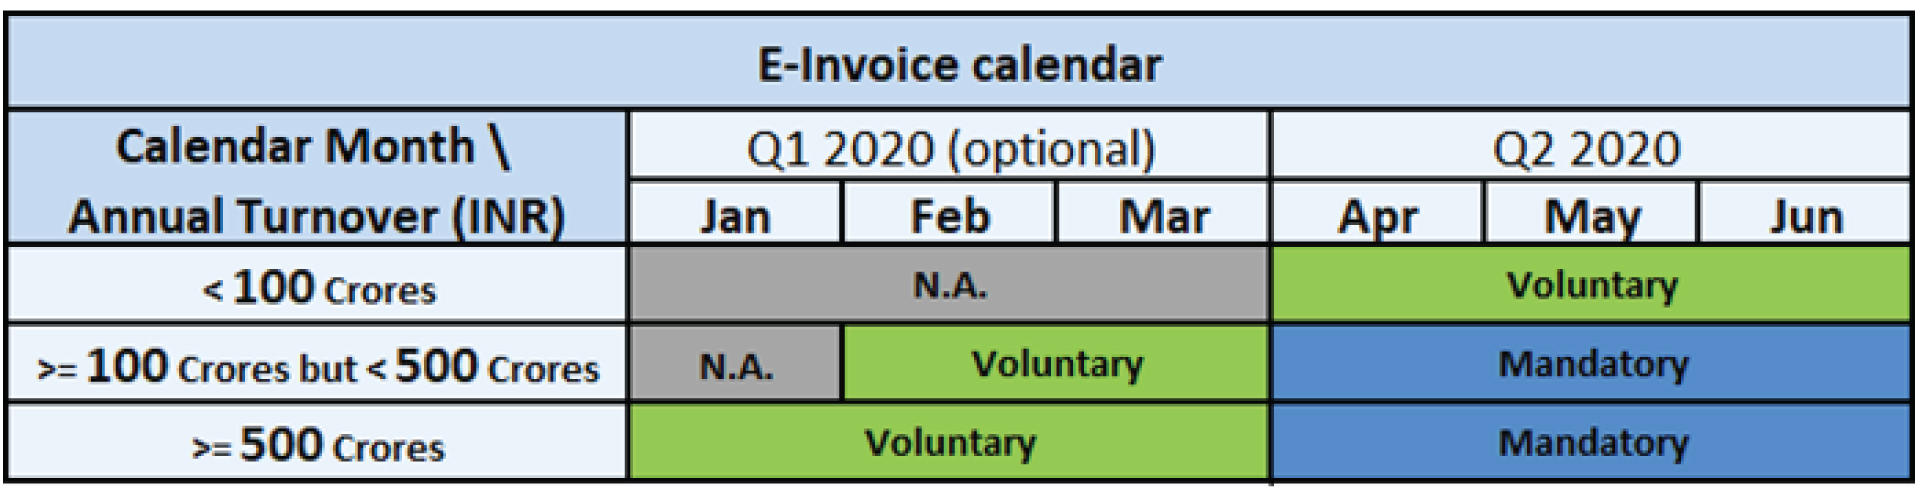
Voluntary e-invoicing
There are taxpayers for whom e-invoicing is voluntary as of April 2020 (based on annual turnover thresholds). We could therefore still have vendor invoices without any e-invoicesto auto-populate the GSTN data. In other words, vendor GST reconciliation would still be relevant for organizations having such vendors in the Accounts Payable cycle.
Changes to e-invoice data
It is best to do the e-invoice generation after ensuring the
correctness and completeness of the invoice data. Well, easier said
than done. There are several taxpayers who dispatch the goods a day
or two after the invoice date. In the exceptional case of any change
in invoice data after the e-invoice is generated, what happens next?
This can still be handled by way of e-invoice cancellation followed
by re-generation of e-invoice with the revised data. However, the
e-invoice cancellation can be handled in the IRP provided the
cancellation is done within 24 hours of the e-invoice
generation.
Beyond 24 hours of e-invoice generation, all further changes have to
be handled in GST ANX-1 and not in e-invoice / IRP. Since this
possibility exists, there would still be a need for GST Returns
solution.
Other sections
E-invoicing is mandatory for specific scenarios:
– Supplier having a specified annual turnover or above
– Customer being a Registered taxpayer or an Export
customer
As can be seen above, B2C is exempted from e-invoice.
While QR code is notified to be mandatory for B2C invoices (for all
suppliers having annual turnover above 500 Crores), there is no
e-invoice for B2C and this QR code is not generated by IRP either.
It is the supplier who has to generate the QR code through alternate
means and incorporate it in the B2C invoice.
This in turn means that the B2C supply information would not get
auto-populated in GST ANX-1 from IRP. Also, a few other sections
like imports would also not be available in the auto-populated GST
ANX-1. These have to be handled by the GST Returns solution.
Similarly, there could be some information that flows into the ERP
often after the invoice is created. The vehicle details (Part B of
the E-Way
Bill for supply of goods) is one such data. The shipping
bill number for Exports is another. These can be handled in E-Way
bill / GST
Returns solutions, if so required.
Continued
Share this Post
Recent Posts

OptiSuite and OptiSuite10x Migration Options
Navigating your journey from legacy SAP ECC systems to modern …Read More »
Driving Enterprise Transformation with Practical Generative AI

Connecting ERP Systems with Government Portals in India – A Practical Guide for Exporters & Importers
In today’s fast-paced global trade environment, Indian exporters and importers …Read More »
OptiVMS by IVL: Advanced SAP Vendor Management System | 30+ Years SAP Expertise
In today’s fast-paced business environment, efficient vendor management is critical …Read More »
Streamline Your SAP Procurement with OptiVMS: The Future of Vendor Management
In the digital era, businesses need agile, efficient, and secure …Read More »
What is RISE with SAP?
RISE with SAP is SAP’s flagship Business Transformation as a …Read More »
OptiSuite10x: The All-in-One SAP Add-On for Indian Enterprises’ Compliance and Trade Needs
For Indian enterprises navigating the complexities of indirect taxation, international …Read More »
Transforming GST Compliance in SAP ERP with IVL’s OptiGST Solution
For Indian enterprises running on SAP ERP, Goods and Services …Read More »
The Importance of the Right Partner for Your SAP BTP Journey

Is Global Trade Operating with Just 3 Documents? Let’s Check the Reality.